Canada made modest progress closing its housing supply gap over the past year, but federal housing officials warn the country could fall further behind just as demand starts to recover, according to new data from Canada Mortgage and Housing Corp.
CMHC’s latest Housing Supply Report, released September 10, estimates that between 417,000 and 469,000 new housing units need to be built annually across ownership and rental markets over the next decade to restore housing affordability to pre-pandemic, 2019 levels by 2036. Over ten years, that adds up to as many as 4.7 million homes. The figure is slightly lower than CMHC’s July 2025 estimate, which called for construction to roughly double to between 430,000 and 480,000 units a year, suggesting the gap between what Canada builds and what it needs has narrowed slightly.
Where the Gap Is Widening and Narrowing
The report, which tracks major census metropolitan areas including Toronto, Vancouver, Montreal, Calgary, Edmonton, Ottawa and Halifax, found sharply different trends by city. The supply gap narrowed in Toronto and held roughly stable in Vancouver, but grew larger in both Montreal and Ottawa. Calgary posted the most notable improvement, with record levels of home construction significantly shrinking its shortfall. Edmonton stood out as the only large Canadian market without a housing supply gap at all.
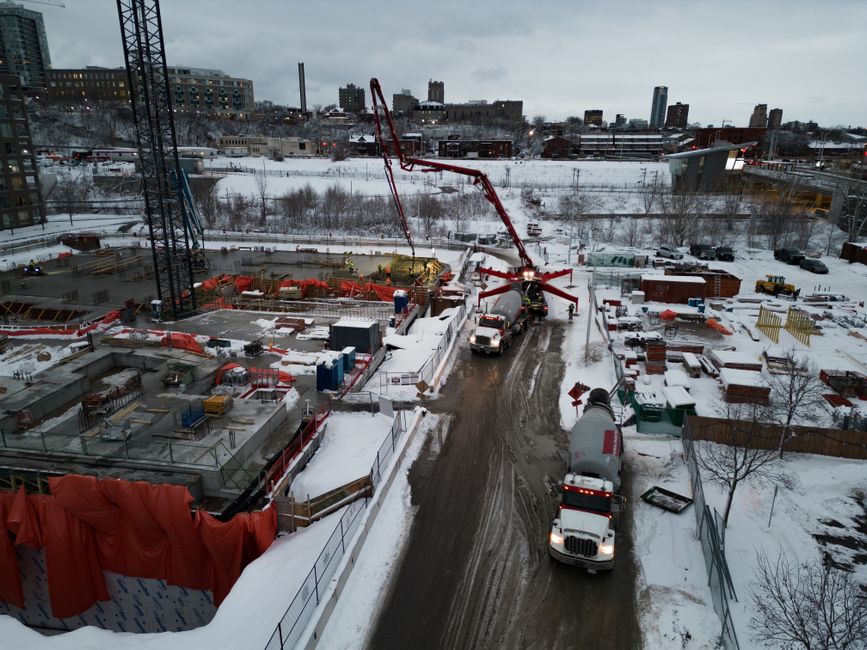
CMHC deputy chief economist Aled ab Iorwerth said the overall improvement in affordability partly reflects slower population growth rather than a fundamental fix to the country’s building capacity. He cautioned that the underlying risk hasn’t gone away. “The key risk now is Canada underbuilds during this softer market and finds itself further short of housing when demand strengthens again,” ab Iorwerth said, according to CMHC’s release. The agency’s report specifically flags that new home construction is expected to slow going forward, particularly in the ownership segment, even as the supply gap remains large.
Why Lower Interest Rates Aren’t the Fix
Separate research from the Bank of Canada adds weight to the argument that supply-side policy, rather than monetary policy, is the more effective lever for affordability. A staff analytical paper published August 20 by Bank of Canada researchers Benjamin Strauss, Stéphane Surprenant and Kerem Tuzcuoglu examined how unexpected interest rate cuts have historically affected home sales, housing starts and prices, using Canadian data from January 1988 to December 2019 sourced from CMHC and the Canadian Real Estate Association.
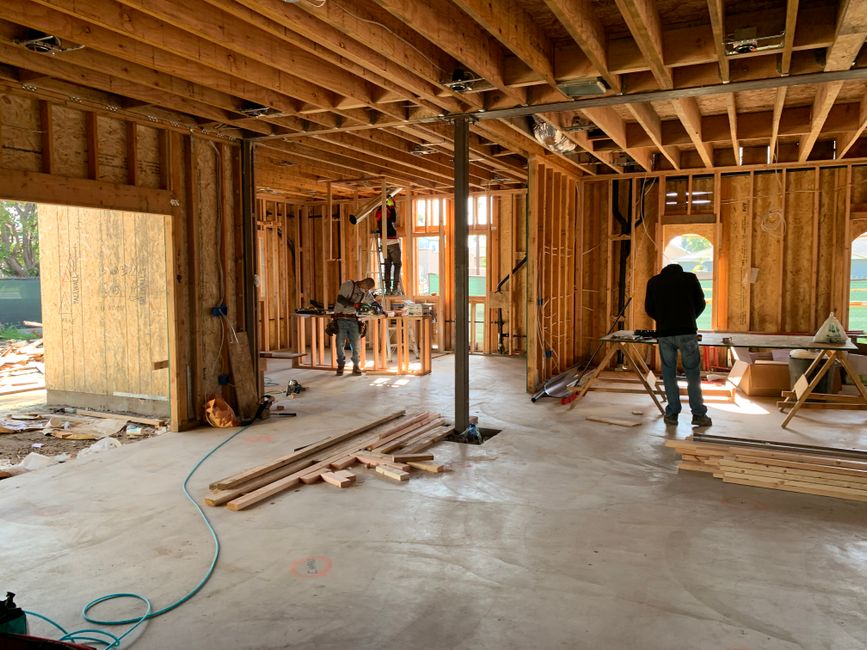
The researchers found that demand for housing reacts to rate cuts far faster than supply does. Home resales pick up shortly after a rate cut, with the strongest effects appearing 18 to 24 months later, while housing starts don’t respond meaningfully until roughly two years out, reflecting the time needed to plan projects, obtain permits and begin construction, especially for multi-unit buildings. Even when new construction eventually follows a rate cut, the researchers found it is not enough to offset the surge in demand. “Because demand tends to respond more strongly than supply, monetary policy appears unable to alleviate housing affordability pressures and may instead intensify them when labour market conditions are strong,” they wrote.
The effect is even more pronounced when unemployment is low. The paper defines a high-unemployment environment as one where the national jobless rate is roughly 7% or higher; below that threshold, rate cuts have a stronger effect on prices and sales relative to supply. Canada’s unemployment rate stood at 6.4% as of July 2025, according to the paper, though the researchers stopped short of drawing explicit conclusions about current conditions. Their bottom line: “policies aimed directly at increasing supply may therefore be more effective than monetary policy at reducing housing-market imbalances.”
Immigration Policy as a Supply-Side Lever
Ottawa’s broader policy response has increasingly focused on the demand side of that equation through immigration levels rather than interest rates. According to reporting on the federal government’s 2026 immigration outlook, Ottawa has moved to rebalance temporary migration alongside housing supply and economic growth goals, an approach officials frame as easing pressure on the housing system while population growth slows. That shift aligns with CMHC’s own observation that slower population growth has been a factor behind recent affordability gains, even as the agency warns those gains are fragile.
Taken together, the CMHC and Bank of Canada findings point to a structural mismatch between how quickly Canada’s housing market can respond to changing conditions and how quickly demand shifts in response to rates, immigration policy or economic cycles. CMHC’s report underscores that even with recent progress, the country remains far short of the construction pace needed to meaningfully close the affordability gap by 2036, with the risk that a slower building environment today could leave fewer homes available whenever demand rebounds.
This article references reporting from: