Cenovus Energy’s agreement to buy Athabasca Oil Corp. for $5.7 billion in cash and stock is, on its face, another oilpatch merger — the kind Albertans have watched unfold for a decade. But look closer and this deal marks something more pointed: the near-completion of a consolidation cycle that has handed Canada’s oilsands to a handful of large-cap operators, just as Ottawa and Edmonton are rewriting the rules to coax more barrels out of the ground.
The Deal Itself
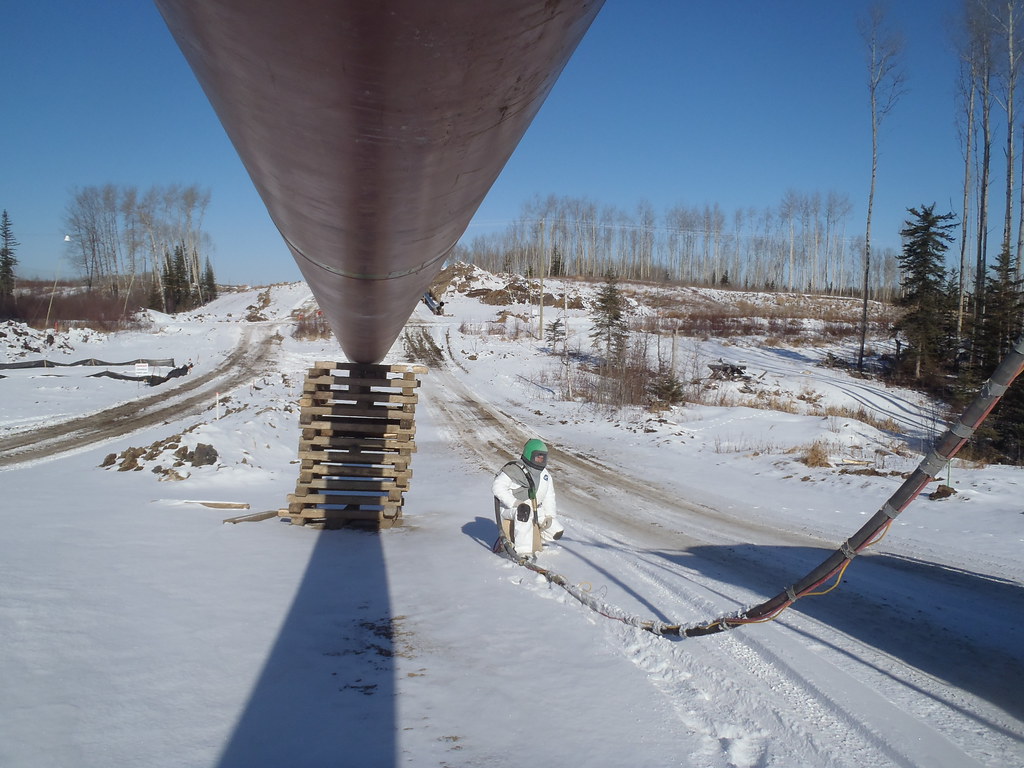
Under the terms announced Monday, Athabasca shareholders can choose $12 in cash or 0.264 of a Cenovus share for every share they hold, with total cash capped at $4.3 billion and Cenovus shares capped at 44.4 million. Cenovus CEO Jon McKenzie told analysts on a conference call that the Athabasca assets represent “one of the most significant organic growth opportunities available in Canadian oilsands today.” Athabasca currently produces about 40,000 barrels per day — Cenovus expects to push that to 115,000 barrels per day by 2032, a near-tripling, anchored by two thermal projects, Leismer and Corner. McKenzie said the company is even looking at advancing the Corner project three years ahead of schedule.
Markets gave a mixed verdict. Cenovus shares fell three per cent to close at $44.86, while Athabasca shares jumped 13.5 per cent to $12.01 — a premium reflecting the deal price. Cole Smead, CEO of Smead Capital, which holds Cenovus shares, called the purchase “aggressive” and expensive, but added: “It’s an expensive move, but it’s an optimistic move. If they’re going to go out and grow production at Athabasca, it means they like the future.”
Why Now: Policy Tailwinds
The timing is not incidental. The deal lands just days after the federal government designated a proposed million-barrel-a-day pipeline from Alberta to British Columbia as the first project under new “national interest” legislation — a designation that fast-tracks regulatory review through a major projects office. McKenzie explicitly linked the acquisition to “positive steps” taken by both Ottawa and Edmonton to boost the sector’s competitiveness, saying they “will have a meaningful impact on our ability to advance growth projects, like the ones we are contemplating at Leismer and Corner.”
He pointed specifically to Prime Minister Mark Carney’s announcement last month allowing businesses to immediately deduct a broader range of capital investments from their taxes, calling the measure “not immaterial” to Cenovus’s ability to accelerate growth. He also cited expected royalty incentives from the Alberta government, slated for announcement in November, designed to spur more oilsands output. “All of that fits together to draw capital back into the resource in the Athabasca Basin and probably accelerate growth as well,” McKenzie said.

A Decade of Consolidation, Reaching Its Logical End
This is not Cenovus’s first big swing. Less than a year ago, the company closed an $8.6-billion acquisition of MEG Energy after a bitter bidding war with Strathcona Resources Ltd. Add Athabasca, and Cenovus’s share of total oilsands output rises to 21.5 per cent, according to a report by energy research firm Wood Mackenzie.
Mark Oberstoetter, head of Americas upstream research at Wood Mackenzie, framed the deal as “the latest step in a decade-long consolidation of Canadian oilsands ownership into the hands of a small number of large-cap Canadian companies,” noting that with this transaction, 90 per cent of oilsands production remains in Canadian hands — and is now more concentrated than ever among the biggest players. Those players — Cenovus, ConocoPhillips, Canadian Natural Resources Ltd., Suncor Energy Inc. and Imperial Oil Ltd. — now dominate the basin.
Michael Berger, senior analyst at Enverus Intelligence Research, noted the price Cenovus is paying sits well above earlier oilsands transactions, a reflection, he argued, of a broader “rerating” of Canadian oilsands producers as the sector’s role in supplying long-term oil in a “resource-constrained world grows sharper.” Scarcity, he wrote, “always demands a premium and logical large-scale oilsands acquisition targets have been significantly drawn down.” His blunter conclusion: “The lack of targets going forward means a hot oilsands (mergers and acquisitions) market may be set to cool.”
Desjardins Securities analyst Robert Mann struck a similar note, writing that while “the transaction does not come cheap,” he views it as “strategically compelling given the scarcity value of top-tier long-duration thermal inventory and the increasingly constructive backdrop for oilsands development.”
Who Wins, Who’s Exposed
Athabasca shareholders are the clearest short-term winners, locking in a roughly 13.4 per cent premium over Friday’s closing price under the $12-per-share cash option. Cenovus, for its part, gains full control of Athabasca’s Duvernay Energy subsidiary, which operates in the Kaybob Duvernay region, where Cenovus plans to lift production to 20,000 barrels of oil equivalent per day — on top of the thermal oilsands growth at Leismer and Corner.
The deal also tests Cenovus’s balance sheet discipline barely a year after the MEG Energy purchase. The stock’s three per cent decline on announcement day suggests at least some investors are wary of the price tag, even as analysts frame the long-duration thermal inventory as scarce and worth paying up for.
There’s a structural question too. As Berger and Oberstoetter both note, the pool of remaining independent oilsands targets is shrinking fast. With Cenovus now holding more than a fifth of total oilsands output, and the sector increasingly concentrated among five companies, the era of frequent, headline-grabbing oilsands takeovers may be approaching its natural limit.
The Bigger Picture: Pipelines, Carbon Capture and a Fed Betting on Growth
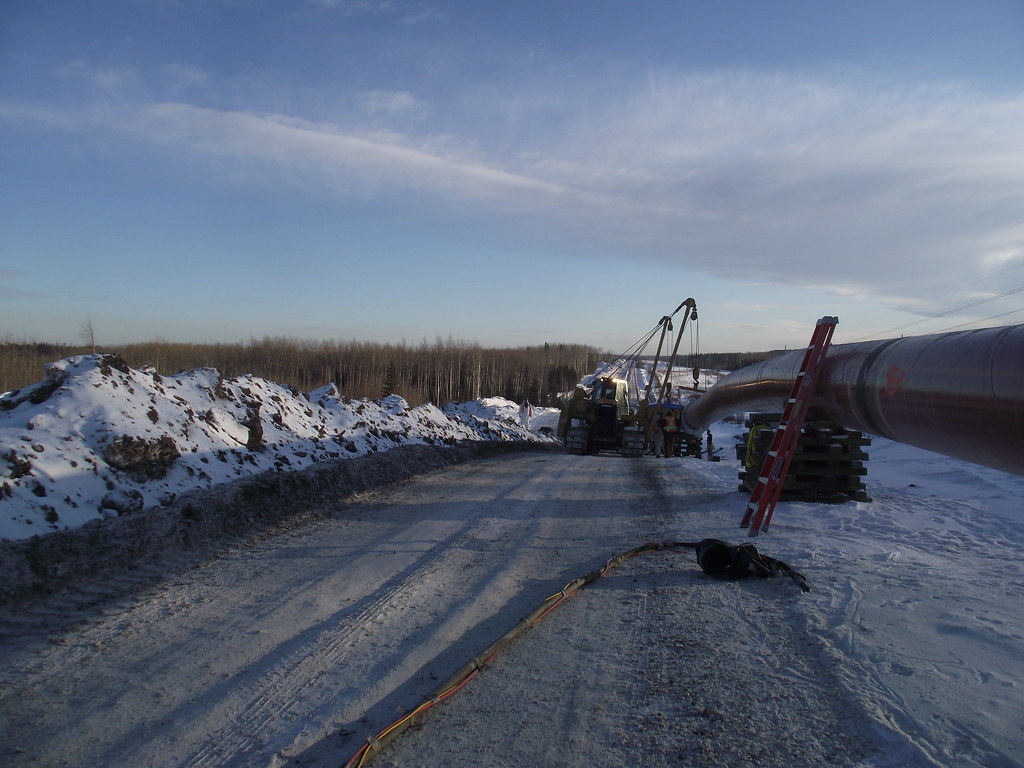
The Athabasca deal cannot be separated from Ottawa’s broader pipeline push. The proposed million-barrel-a-day line to the B.C. coast is meant to come online around 2032 — the same year Cenovus is targeting for Athabasca’s production ramp-up — alongside several other expansions arriving sooner. There have been persistent questions, raised in the reporting itself, about whether oilsands producers would actually invest enough in new production to fill that capacity. Cenovus’s bet on Leismer and Corner is, in effect, a partial answer: yes, if the policy environment cooperates.
But the full picture remains incomplete. Major oilsands companies, including Cenovus, have yet to reach a final investment decision on a large-scale carbon capture and storage project that is widely viewed as a prerequisite for the pipeline’s advancement. That unresolved piece — far more capital-intensive and politically fraught than a single corporate acquisition — looms over the entire growth thesis analysts are now pricing into oilsands valuations.
Our Take
In our view, this deal says less about Athabasca Oil specifically and more about where Canada’s energy policy and its largest producers currently align. Cenovus is making a leveraged bet that Ottawa’s tax changes, Alberta’s forthcoming royalty incentives, and a fast-tracked pipeline designation will combine to make thermal oilsands growth genuinely profitable by the early 2030s — not just permitted, but economic. That’s a reasonable wager given the policy signals described above, but it is still a wager: royalty details haven’t been announced, the carbon capture investment decision hasn’t been made, and the pipeline itself is years from operation.
The more interesting question, raised implicitly by Berger’s comments, is what happens to M&A activity in the basin once there’s effectively no one left to buy. With five companies now controlling the overwhelming majority of oilsands output, future growth will likely have to come from internal capital spending rather than acquisitions — which puts even more weight on whether the tax and royalty incentives McKenzie cited actually translate into shovels in the ground. For Canadian consumers and taxpayers, the stakes are less about this one transaction than about whether a smaller number of very large companies steering a resource this concentrated serves the public interest as well as competition among many did. For Cenovus’s own shareholders, the market’s muted reaction on deal day suggests the jury is still out on whether a second multibillion-dollar oilsands purchase in twelve months was prudence or overreach.
This is a Commentary piece: analysis and editorial perspective from Canadian Business News, clearly distinguished above from the reported facts it’s based on. It is not financial, investment, or legal advice.
Sources